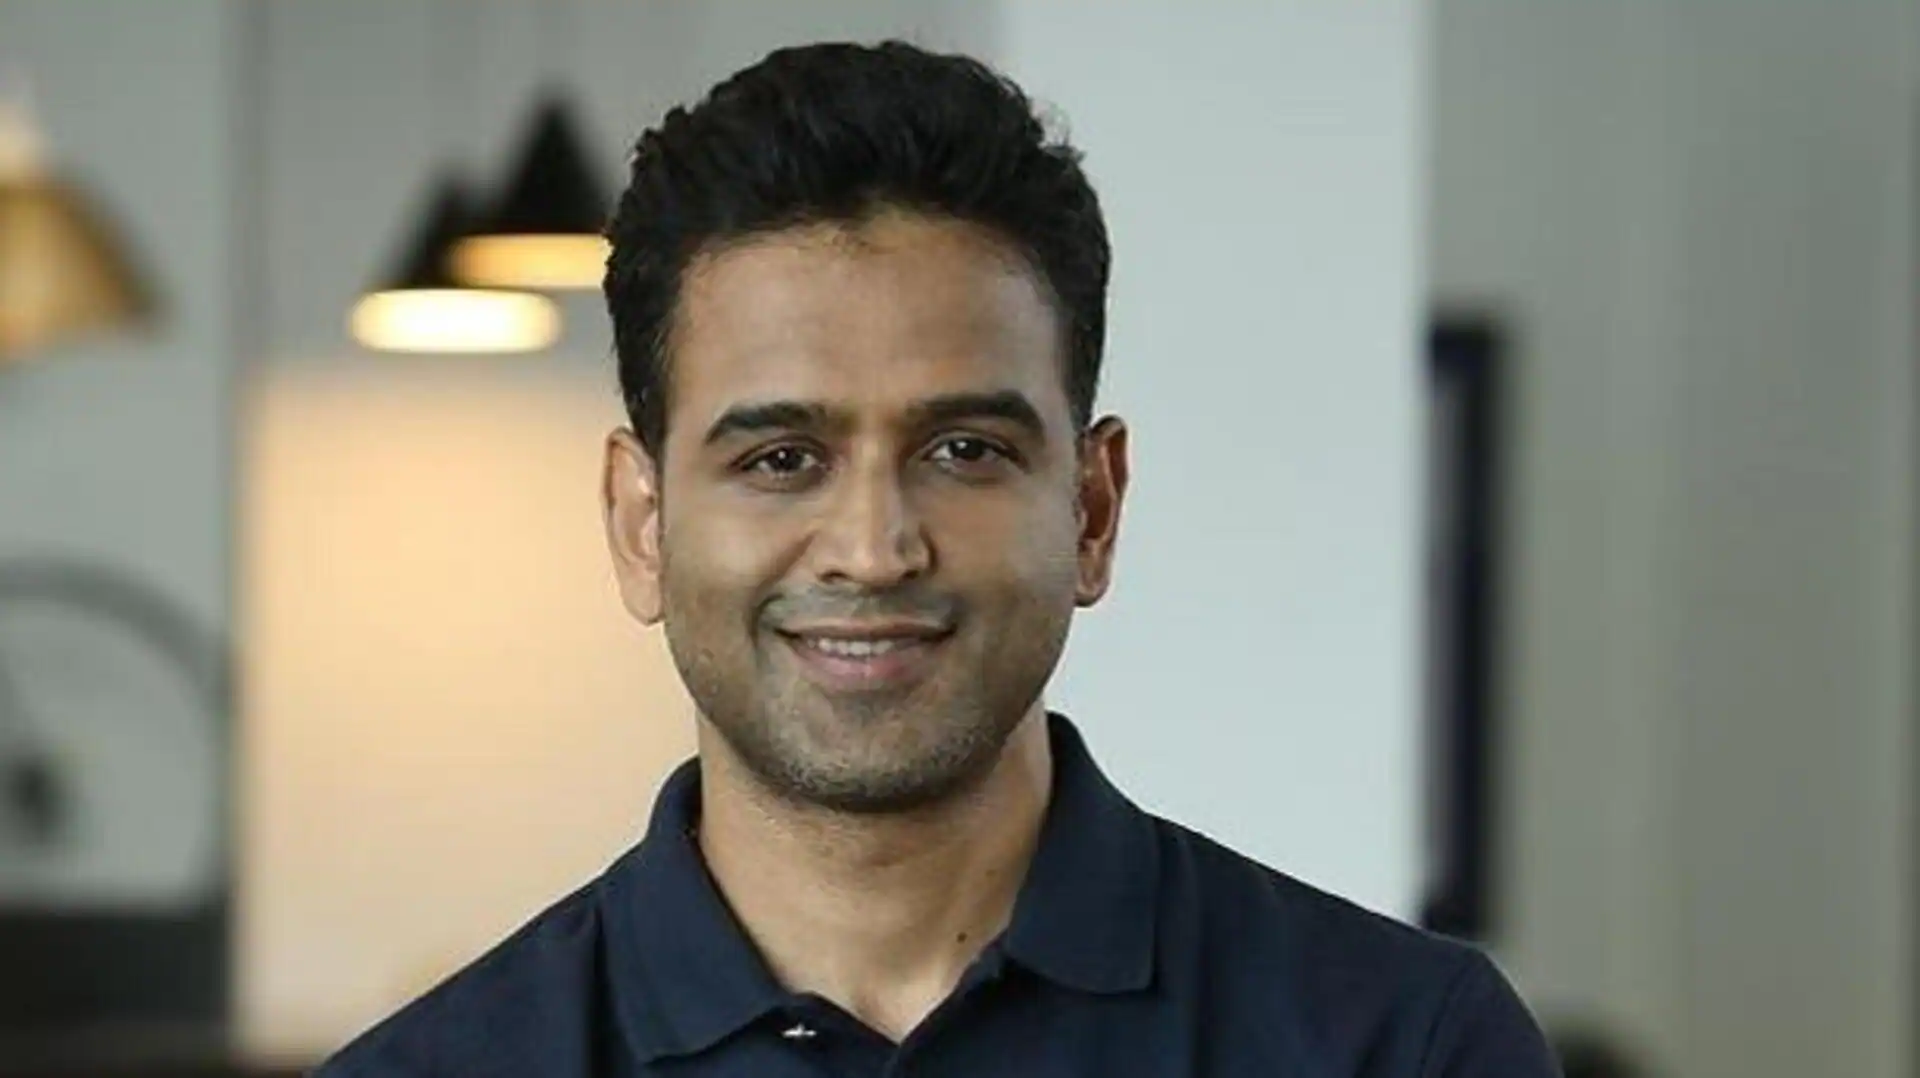
Nithin Kamath Flags Liquidity Risks in India's MTF Market
Nithin Kamath warns that small-cap stocks account for nearly half of India's MTF exposure, raising concerns over liquidity, leverage and market volatility.
Zerodha co-founder and CEO Nithin Kamath has raised fresh concerns about liquidity risks in India's stock market, warning that the growing concentration of margin trading facility (MTF) exposure in small-cap and micro-cap stocks could create challenges for investors and brokerage firms during a market downturn. In a post on X on October 9, 2026, Kamath highlighted the risks associated with leveraged investments in smaller companies, where liquidity can decline rapidly when markets weaken or move sideways. The warning has brought renewed attention to the relationship between borrowing, stock market volatility and the ability of investors to exit positions during periods of financial stress.
According to data shared by Kamath and reported by The Economic Times, small-cap stocks account for approximately 50% of India's margin trading facility book, while large-cap stocks represent around 32% and mid-cap stocks account for approximately 18%. The figures highlight the extent of funded exposure to smaller companies and raise questions about how effectively leveraged positions could be managed if selling pressure increases. Although margin trading allows investors to participate in the market with borrowed funds, concentrated exposure to less liquid securities can increase risks for both customers and brokers.
Kamath's warning is particularly relevant as investors continue to explore ways to increase their market exposure through borrowing. While leverage can improve potential returns when share prices rise, it can also magnify losses when prices fall. The problem becomes more complicated when investors hold stocks that have limited trading volumes or face lower price circuits, conditions that can make it difficult to sell shares quickly. For brokerage firms that finance these positions, an inability to liquidate collateral promptly could create additional financial and operational pressure.
Nithin Kamath Warns About Growing Small-Cap Exposure in Margin Trading
Nithin Kamath's latest comments focus on the changing composition of India's margin trading facility market. MTF enables investors to purchase shares by paying part of the investment amount themselves while borrowing the remaining funds from a broker. The purchased securities generally serve as collateral for the financing arrangement, and investors must comply with applicable margin requirements and other conditions.
The concern highlighted by Kamath is not simply the expansion of margin trading but the concentration of funded investments in smaller companies. Small-cap and micro-cap stocks can experience greater price fluctuations when market sentiment changes because their trading activity and available buyers may be more limited than those of large, actively traded companies. When investors attempt to sell their holdings simultaneously, the available market liquidity may not be sufficient to absorb the additional supply without substantial price movements.
In his October 9 post, Kamath pointed out that most of the growth in the industry's MTF book has been concentrated in small-cap and micro-cap stocks. He warned that liquidity in these securities tends to dry up first when markets decline or move sideways. This observation highlights a potential weakness in leveraged investing: investors may be able to purchase shares easily during favourable market conditions but could find it considerably harder to sell those same shares when market sentiment deteriorates.
The warning also draws attention to the importance of evaluating the underlying assets used as collateral for margin financing. A portfolio containing liquid, actively traded stocks may behave differently from one concentrated in smaller companies during a period of market stress. Consequently, the amount of money lent against a portfolio is only one part of the risk equation; the ability to recover that money through the sale of securities is equally important.
What the Latest MTF Data Reveals About India's Stock Market
The figures highlighted in the latest report provide a closer look at how India's margin trading exposure is distributed across companies of different market capitalisations. According to The Economic Times, the data shared by Kamath showed that large-cap stocks ranked among the top 100 companies by market capitalisation accounted for around 31% of the funded book in one classification of the exposure. Mid-cap stocks ranked 101–250 represented approximately 17%.
The distribution among smaller companies was more fragmented. Small-cap stocks ranked 251–500 accounted for about 20% of the funded book, while micro-cap stocks ranked 501–750 represented around 14%. Stocks ranked 751 and beyond accounted for another 15%, while securities outside the relevant Association of Mutual Funds in India (AMFI) list made up approximately 4%.
These figures illustrate why aggregate market statistics may not fully capture the risks associated with margin financing. A market can appear relatively stable at the index level even when certain segments are experiencing weaker liquidity or greater selling pressure. If leveraged investments are concentrated in those segments, a sudden reversal could create difficulties that are not immediately apparent from the performance of major indices.
The reported data was based on National Stock Exchange margin trading disclosures at the individual-security level and AMFI market-capitalisation classifications. The index-performance comparison used total-return indices. The distinction between funded exposure and index performance is important because the two measures describe different aspects of the market: one reflects how borrowed investment funds are distributed, while the other tracks the performance of defined groups of securities.
For investors and brokerage firms, the key question is whether the liquidity available in individual securities would remain sufficient under adverse market conditions. A concentration of exposure does not automatically mean that a market crisis will occur, but it does identify an area where risk monitoring and stress testing become particularly important.
Understanding Margin Trading Facility and Its Risks
Margin Trading Facility has become an important feature of India's retail investing ecosystem, allowing eligible investors to increase their exposure to equities without paying the entire purchase price upfront. Under this arrangement, a broker finances part of the investment, while the customer contributes the remaining amount and remains responsible for meeting the applicable obligations.
For example, consider an investor purchasing shares worth ₹1 lakh by contributing ₹25,000 and borrowing ₹75,000, assuming such a funding arrangement is permitted. The investor gains exposure to the full ₹1 lakh position even though only ₹25,000 was contributed initially. If the shares appreciate, the return relative to the investor's own contribution may be higher than it would have been without borrowing.
However, the same mechanism works in reverse when prices decline. A 10% fall in the value of the ₹1 lakh position would reduce the holding's value to ₹90,000, representing a ₹10,000 loss before interest, fees and other charges. That loss would equal 40% of the investor's original ₹25,000 contribution, illustrating how leverage magnifies the impact of a market movement.
A more severe decline could create an even greater financial burden. Investors may need to add funds, reduce their holdings or meet other requirements imposed under the applicable financing arrangement. If they fail to satisfy the required conditions, the broker may take action to reduce or close the position in accordance with its policies and relevant regulations.
The risks are not limited to the investor. Brokers also need to recover the money they have lent, which means the value and liquidity of the securities held as collateral are crucial. If the market price falls sharply and the stock cannot be sold at a reasonable price, the amount recovered from liquidation may be insufficient to cover the outstanding financing.
This makes margin trading a risk-management issue for the entire brokerage ecosystem rather than merely an investment choice for individual customers.
Why Small-Cap and Micro-Cap Stocks Face Greater Liquidity Challenges
Small-cap and micro-cap stocks can attract investors because of their potential for business expansion, earnings growth and increased market recognition. However, these opportunities can come with higher volatility and lower trading liquidity. Smaller companies may have fewer shares actively traded on a daily basis, and the number of market participants willing to buy during uncertain periods can decline rapidly.
Liquidity refers to how easily an asset can be bought or sold without causing a significant change in its price. In a liquid stock, a large number of buyers and sellers generally participate in the market, allowing transactions to take place with relatively limited price disruption. In a less liquid stock, even a moderately large order can move the price considerably.
The difference becomes especially important during market corrections. When investors become concerned about falling valuations or deteriorating economic conditions, they may try to reduce their exposure at the same time. If selling orders exceed the available demand, prices can fall sharply. Investors who need to sell quickly may have to accept less favourable prices than they initially expected.
For leveraged investors, this problem is more serious because their positions are supported by borrowed funds. Falling prices reduce the value of their collateral, potentially creating margin shortfalls. At the same time, limited liquidity can prevent them from selling their holdings quickly enough to meet their obligations or reduce their exposure.
Micro-cap stocks can be particularly vulnerable when trading activity becomes concentrated among a small number of market participants. A reduction in buying interest may cause substantial price movements, while a lack of counterparties can delay the execution of sell orders. These conditions can make it more difficult for brokers to recover their loans by selling pledged shares.
The concern raised by Kamath therefore centres on the interaction between stock selection, market liquidity and leverage. A stock's potential for long-term growth does not necessarily mean that it will remain easy to sell during a period of financial uncertainty.
How Lower Price Circuits Can Complicate Forced Selling
One of the major concerns associated with less liquid stocks is the possibility of lower price circuits. Indian exchanges impose price bands and circuit limits on securities under applicable rules to manage extreme price movements and orderly trading. When a stock reaches its lower price limit, further trading at lower prices may not be possible during that session, and selling interest may exceed available buying interest.
For an investor holding shares without borrowed funds, such a situation may be uncomfortable but does not necessarily create an immediate financing obligation. An investor using MTF, however, must also consider the outstanding loan, applicable interest and the broker's margin requirements.
If the collateral value continues to decline, the broker may need to reduce its exposure. Yet a lower circuit accompanied by a shortage of buyers can prevent the broker from selling the shares as quickly as required. The result is a mismatch between the need to manage the loan and the practical ability to liquidate the underlying asset.
This is why liquidity risks cannot be measured solely by looking at a stock's recent price performance or market capitalisation. Trading volume, order-book depth, the distribution of ownership and the behaviour of buyers during market stress can all influence how easily a position can be closed.
Price circuits are not evidence that a stock will necessarily become impossible to sell. Their effect depends on the security, applicable exchange rules and actual market conditions. Nevertheless, when lower circuits coincide with substantial selling pressure, they can make the management of leveraged positions more complicated.
For brokerage firms, these conditions reinforce the importance of assessing the liquidity of collateral before extending financing and monitoring it throughout the life of a position.
How Leverage Can Turn a Market Correction Into a Larger Sell-Off
Leverage can contribute to a self-reinforcing cycle during periods of market stress. When stock prices rise, the value of investors' holdings may increase, improving the value of collateral and potentially enabling them to take on additional exposure. As borrowing expands, more capital becomes linked to market prices.
This process can support demand during a rising market. However, when prices reverse, the same mechanism can amplify the downward movement. Declining stock values reduce collateral coverage, which may lead to margin calls, position reductions and forced selling.
When multiple investors hold leveraged positions in the same stocks, their efforts to reduce risk can increase the supply of shares available for sale. If buyers are unwilling or unable to absorb that supply, prices may fall further. The decline can then trigger additional margin shortfalls, creating another round of selling pressure.
Small-cap and micro-cap stocks may be more vulnerable to this process because their available liquidity can be lower than that of large-cap companies. A relatively modest amount of forced selling can have a significant impact when market depth is limited.
Kamath's warning about India's MTF exposure is therefore connected to a broader market risk: the possibility that leverage could intensify price movements when investors attempt to exit positions simultaneously. The concern is not that every decline will produce a crisis, but that concentrated borrowing in less liquid securities could make a difficult market environment harder to manage.
What the Warning Means for Brokerage Firms
The expansion of margin trading creates business opportunities for brokerage firms, including interest income and increased customer activity. However, these benefits must be balanced against the financial risks associated with lending against market-linked collateral.
When brokers finance stock purchases, they need to assess the amount of money advanced, the customer's contribution, the value of the collateral and the potential speed of price movements. They must also account for the possibility that the securities may become difficult to sell precisely when repayment becomes most important.
A rapid increase in MTF exposure can make these considerations more significant, particularly if a substantial portion of funded positions is concentrated in stocks with limited liquidity. If the market declines, brokers may face simultaneous requests for additional margin from customers and reduced opportunities to liquidate collateral.
One important risk-management measure is portfolio stress testing. Brokerage firms can evaluate how their funded books might perform under scenarios involving sharp price declines, reduced trading volumes and widespread selling. Such analysis can help identify concentrations that may become problematic when market conditions change.
Another consideration is the quality of risk limits and collateral monitoring. Brokers need to ensure that their internal systems accurately track positions, calculate margin requirements and identify accounts that require attention. The ability to respond quickly is important, but it must operate alongside appropriate lending policies and clear customer communication.
Kamath's warning highlights the importance of evaluating the overall quality of a brokerage firm's funded portfolio rather than focusing exclusively on the size of its MTF business. Growth in lending may support revenue, but the associated risks need to be understood and controlled.
Why Investors Should Pay Attention to Borrowing Costs and Margin Calls
For retail investors, MTF can appear attractive because it allows them to purchase more shares than they could afford using only their available capital. However, the apparent advantage of increased purchasing power should be evaluated against the additional risks and costs involved.
Borrowing typically attracts interest, and the total cost depends on the broker's terms, the amount financed and the duration of the position. Investors must consider these charges when estimating the potential return from a trade or investment. Even if a stock's price remains relatively stable, borrowing costs can reduce the overall profitability of the position.
Margin calls are another important consideration. When a position loses value or the applicable margin requirement changes, investors may be required to provide additional funds or reduce their holdings. If they cannot meet the requirement, the broker may liquidate some or all of the position according to the terms of the facility and applicable policies.
Market conditions can make this process more difficult. During a period of high volatility, prices may change rapidly, and the final execution price may differ significantly from the price an investor expected. In less liquid securities, the difference can be more pronounced.
Investors should therefore understand the funding terms, interest charges, collateral requirements and liquidation policies before using borrowed money to purchase shares. They should also consider whether they could manage a substantial decline without relying on the immediate sale of a particular security.
The warning does not mean that all margin-funded investments are inherently unsuitable. Instead, it underlines the importance of understanding how leverage changes the financial consequences of an investment decision.
The Role of SEBI and Market Risk Controls
The expansion of margin trading also raises questions about the role of market safeguards and regulatory oversight. India's securities market operates under a framework of rules governing margin requirements, broker conduct, risk management and trading practices. These mechanisms are intended to support orderly markets and reduce the risks associated with excessive exposure.
Effective risk controls require more than monitoring the overall amount of money borrowed. The liquidity and volatility of individual securities, the concentration of exposures and the ability to meet margin obligations can all influence the risk associated with a funded position.
Market participants must also distinguish between the existence of leverage and the concentration of leverage in vulnerable assets. Borrowing against highly liquid securities may present a different set of risks from borrowing against smaller stocks that experience sharp price movements and limited trading activity.
Kamath's comments bring this distinction into focus by highlighting the share of MTF exposure directed towards small-cap and micro-cap stocks. The data can inform discussions about risk management, disclosure and the importance of monitoring market-wide funding trends.
Any regulatory response would need to be considered within the applicable securities-market framework and supported by evidence about the nature and scale of the risks. The concentration figures alone do not establish that a regulatory change is necessary, but they provide a reason for investors, brokers and market observers to pay closer attention to liquidity conditions.
How Financial Technology Can Help Monitor Liquidity Risks
The concerns raised by Kamath also demonstrate the growing importance of financial technology in brokerage operations. As trading platforms expand and investors gain access to more sophisticated financial products, firms need reliable systems to monitor customer positions, collateral values and market movements.
Modern financial software can integrate information from trading platforms, risk-management systems and market-data feeds. By bringing these sources together, firms can obtain a clearer picture of their exposure and identify positions that may require closer attention.
Automated monitoring tools can help track changes in portfolio value, calculate margin utilisation and generate alerts when defined risk thresholds are reached. Such systems can support operational efficiency by reducing reliance on manual checks and improving the consistency of risk reporting.
Data analytics can also help firms identify concentration risks across individual securities, market-capitalisation categories and customer accounts. Stress-testing tools can model hypothetical scenarios involving falling prices, lower trading volumes and simultaneous margin shortfalls, helping risk teams understand where weaknesses may emerge.
However, technology is only one component of an effective risk-management framework. Accurate data, sensible lending limits, appropriate collateral policies and well-defined escalation procedures remain essential. An automated system cannot guarantee that a stock can be sold during a market disruption, nor can it eliminate losses caused by sudden price movements.
For fintech companies and software developers serving financial institutions, the challenge is to build systems that provide timely, reliable and actionable information. As financial markets become more interconnected, robust technology infrastructure can help firms identify emerging risks and make better-informed operational decisions.
What Businesses and Fintech Companies Can Learn From the Warning
The broader lesson from Kamath's warning extends beyond stock trading. Financial institutions increasingly depend on technology to manage large volumes of transactions, monitor risk and make decisions under changing market conditions. When exposure grows faster than the systems and controls designed to manage it, operational weaknesses can become more consequential.
Businesses operating in financial services need to ensure that their software infrastructure supports visibility, accountability and timely intervention. Data should be accurate and accessible, risk indicators should be meaningful, and decision-makers should be able to identify concentrations before they become difficult to manage.
This principle also applies to other sectors that rely on credit, working capital or short-term financing. A business may appear financially healthy during favourable conditions but encounter difficulties when cash flow slows, counterparties delay payments or assets become harder to convert into cash.
Liquidity management is therefore not simply a matter of holding sufficient funds. It also involves understanding when money may be needed, how quickly assets can be converted into cash and what could happen if several adverse events occur simultaneously.
For technology providers, these challenges create an opportunity to develop solutions that improve financial visibility and risk monitoring. Yet the value of those solutions depends on their integration with sound business processes and appropriate governance.
What Could Happen if Market Conditions Weaken Further?
The impact of India's growing MTF exposure will depend on how market conditions evolve, how investors respond to volatility and how effectively brokers manage their funded positions. A stable or improving market may allow many leveraged positions to remain manageable. A sharp decline, however, could test the liquidity of smaller stocks and the ability of market participants to meet their financial obligations.
If investors begin reducing their exposure simultaneously, the first effects may appear in securities with limited trading activity. Wider differences between buying and selling prices, lower trading volumes and sharp price movements could make it more expensive to exit positions.
If these conditions coincide with falling collateral values, investors may face greater pressure to add funds or close positions. Brokers, in turn, may need to reassess their exposure and manage the possibility that collateral cannot be liquidated immediately.
It is important to distinguish these potential outcomes from a prediction that a crash is imminent. Kamath's warning identifies vulnerabilities in the current distribution of funded exposure; it does not establish that a severe market downturn will necessarily occur. The eventual impact would depend on the scale of any price decline, the liquidity available in individual stocks and the resilience of the risk controls used by market participants.
Investors and brokers should therefore treat the warning as a reminder to examine potential downside scenarios rather than as a definitive forecast of future market performance.
Conclusion: Nithin Kamath's Warning Highlights the Importance of Liquidity Management
Nithin Kamath's latest warning about liquidity risks in India's margin trading market highlights the potential vulnerabilities created by concentrated leverage in small-cap and micro-cap stocks. With small-cap stocks accounting for approximately half of the industry's MTF exposure in the reported figures, the ability to manage positions during periods of market stress has become an important consideration for investors and brokerage firms.
Margin trading can provide investors with greater purchasing power, but it also magnifies losses and introduces borrowing costs, collateral requirements and the possibility of forced liquidation. These risks can become more difficult to manage when the underlying securities have limited trading liquidity or encounter lower price circuits during a sell-off.
For brokerage firms, the challenge is to balance the commercial opportunities associated with margin financing against the need for disciplined lending, reliable collateral monitoring and effective stress testing. For investors, the priority should be understanding the risks of leverage and ensuring that investment decisions account for the possibility of sudden market declines.
The warning also reinforces the importance of technology in modern financial risk management. Real-time monitoring, accurate data and automated alerts can improve visibility into funded positions, but they must be supported by sound policies and appropriate controls.
Ultimately, the issue raised by Kamath is not merely about the growth of margin trading. It is about whether market participants can manage their exposure when liquidity becomes scarce. As India's financial markets continue to evolve, the ability to recognise and manage liquidity risk will remain essential to responsible investing and a resilient brokerage ecosystem.
To read more such news kindly visit: Startuptimes
Leave a comment
Your email address will not be published. Required fields are marked *
Add a newsletter to your widget area.
Top Stories